' fill='%23fff' stroke='%23707070' d='M0 0h21.6v21.6H0z'/%3e%3c/clipPath%3e%3cclipPath id='c'%3e%3cpath data-name='Rectangle 6531' transform='translate(-6319 -2048)' fill='%23fff' stroke='%23707070' d='M0 0h43.2v21.6H0z'/%3e%3c/clipPath%3e%3cclipPath id='a'%3e%3cpath d='M0 0h21.6v21.6H0z'/%3e%3c/clipPath%3e%3c/defs%3e%3cg data-name='Malaysia -Square' clip-path='url(%23a)'%3e%3cpath fill='%23fff' d='M0 0h21.6v21.6H0z'/%3e%3cg data-name='Mask Group 325' transform='translate(6348 2048)' clip-path='url(%23b)'%3e%3cg data-name='Mask Group 324' transform='translate(-35)' clip-path='url(%23c)'%3e%3cg data-name='Group 21195'%3e%3cpath data-name='Path 14718' d='M-6319-2048h43.2v21.6h-43.2z' fill='%23fff'/%3e%3cpath data-name='Path 14719' d='M-6317.457-2047.229h41.657m0 3.086h-41.657m0 3.086h41.657m0 3.086h-41.657' fill='none' stroke='%23c00' stroke-width='1.543'/%3e%3cpath data-name='Path 14720' d='M-6319-2048h21.6v13.114h-21.6z' fill='%23006'/%3e%3cpath data-name='Path 14721' d='M-6319-2034.886h43.2m0 3.086h-43.2m0 3.086h43.2' fill='none' stroke='%23c00' stroke-width='1.543'/%3e%3c/g%3e%3cpath data-name='Path 14722' d='M-6302.5-2045.686l.344 2.353 1.331-1.967-.714 2.269 2.054-1.2-1.626 1.731 2.372-.19-2.218.858 2.218.858-2.372-.19 1.626 1.736-2.054-1.2.714 2.269-1.331-1.97-.344 2.358-.344-2.353-1.331 1.97.714-2.269-2.054 1.2 1.626-1.737-2.372.19 2.218-.858-2.218-.859 2.372.19-1.626-1.736 2.054 1.2-.714-2.267 1.331 1.97zm-1.929.1a4.114 4.114 0 100 7.521 4.629 4.629 0 110-7.521z' fill='%23fc0'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "malaysiaIcon")
'%3e%3cpath fill='%23fff' d='M0 0h21.6v21.6H0z'/%3e%3cg data-name='067-hong-kong'%3e%3cpath data-name='Rectangle 6488' fill='%23d80027' d='M0 0h22v22H0z'/%3e%3cg data-name='Group 21086' fill='%23f0f0f0'%3e%3cpath data-name='Path 14432' d='M11.911 8.264c-.248 1.032-.689.835-.905 1.735a2.373 2.373 0 011.109-4.614c-.429 1.803.018 1.956-.204 2.879z'/%3e%3cpath data-name='Path 14433' d='M8.606 9.029c.9.555.581.913 1.37 1.4a2.373 2.373 0 01-4.045-2.481c1.577.964 1.866.586 2.675 1.081z'/%3e%3cpath data-name='Path 14434' d='M8.311 12.409c.807-.689 1.048-.271 1.752-.871a2.373 2.373 0 11-3.609 3.081c1.408-1.202 1.136-1.594 1.857-2.21z'/%3e%3cpath data-name='Path 14435' d='M11.435 13.734c-.406-.98.066-1.08-.287-1.935a2.373 2.373 0 111.815 4.385c-.708-1.71-1.165-1.573-1.528-2.45z'/%3e%3cpath data-name='Path 14436' d='M13.66 11.173c-1.058.083-1.007-.4-1.929-.325a2.373 2.373 0 114.731-.371c-1.846.145-1.856.621-2.802.696z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "hongKongIcon")


Asia Semiconductors

Singapore

South Korea

Taiwan

Asia ex-Japan

GEMs

China

Hong Kong

Semiconductors

Digital Economy

Malaysia

Japan

Global Healthcare

India

Global Financials

ASEAN

Europe

US
Star Ratings
What is FSM Star Ratings?Learn more
In our Star Rating exercise, we look at key valuation metrics like PE and PB ratios, expected earnings growth, along with excess earnings yield to determine how attractive a particular market is. In addition, we consider the economic outlook, generation reforms as well as fiscal and monetary policies in a particular market and tie those stories with our estimates. The Star Rating reflects the upside potential of a market, which is inclusive of valuation expansion, expected earnings as well as expected dividends.
Very Attractive - 5.0 To 4.0 Stars
Asia Semiconductors
We remain highly positive on Asian semiconductors, supported by robust AI hardware and memory demand, with supply constraints expected through 2027. Strong demand across memory, foundry and semiconductor equipment supports pricing power and earnings growth, while multi-year supply agreements provide greater visibility. With the Asian semiconductor sector offering a significant valuation discount to US peers, we maintain our 4.5-star “Very Attractive” rating.
Asia SemiconductorsSingapore
Singapore’s economy remains supported by the AI-led electronics upcycle, strong export growth and contained inflation. Resilient bank and industrial earnings, alongside semiconductor investments and data-centre expansion, support market performance and create opportunities among small- and mid-cap companies. As global equity markets become increasingly concentrated in technology stocks, Singapore offers valuable portfolio diversification. We maintain our 4.0-star “Very Attractive” rating.
South Korea
South Korean equities remain supported by a sustained memory upcycle and record profitability at Samsung Electronics and SK Hynix. Firm DRAM and NAND pricing, alongside multi-year supply agreements, underpin earnings visibility and margins, while rising AI data-centre investment provides an additional demand driver. With the AI investment thesis intact and opportunities extending beyond AI, we maintain our 4.0-star “Very Attractive” rating on South Korean equities.
Taiwan
Taiwan equities remain supported by robust AI-driven semiconductor demand, with TSMC's record revenue growth and pricing power strengthening earnings prospects. Persistent capacity constraints, orders secured through 2027 and expanding AI investment provide greater earnings visibility, while strong exports support economic growth. With earnings forecasts rising faster than the index, valuations have become more attractive. As such, we maintain our 4.0-star “Very Attractive” rating.
Asia ex-Japan
Asia ex-Japan equities remain supported by AI-driven semiconductor demand, led by strong earnings growth in Taiwan and South Korea, with China’s technology and Singapore’s industrials sectors also benefiting. Earnings growth is broadening, while forward P/E valuations have fallen to one standard deviation below their 10-year average. With improving fundamentals and more attractive valuations, we upgrade Asia ex-Japan equities to 4.0 stars “Very Attractive”.
GEMs
Similar to Asia ex-Japan, emerging market equities continue to benefit from strong semiconductor-led earnings momentum in North Asia, alongside broadening earnings growth beyond technology in China. With improving earnings fundamentals and attractive valuations, we also upgrade emerging market equities to 4.0 stars “Very Attractive”.
SingaporeSouth KoreaTaiwanAsia ex-JapanGEMsAttractive - 3.5 To 3.0 Stars
China
China's K-shaped recovery continues, with AI, semiconductors and high-tech manufacturing driving growth while property investment and domestic consumption remain weak. Resilient exports, improving industrial profitability and targeted policy support underpin the technology-led expansion. As such, we maintain our 3.5-star “Attractive” rating on China equities, reflecting structural growth opportunities despite an uneven economic recovery.
Hong Kong
Hong Kong equities remain supported by mainland China's resilience, improving corporate earnings and sustained southbound capital inflows. Easing competition among internet platforms supports margin recovery, while growing IPO activity in AI, semiconductors and biotechnology provides additional catalysts. With valuations remaining reasonable, we maintain our 3.5-star “Attractive” rating on Hong Kong equities, reflecting improving earnings prospects and further upside potential.
Semiconductors
While elevated valuations previously kept us cautious, stronger guidance has extended the AI earnings runway, and persistent supply constraints across foundry and memory continue to support pricing and profitability. With valuations now lower after the July correction, we see a more attractive entry point to add semiconductor exposure heading into 4Q26. As such, we upgrade the semiconductor sector from 2.5 stars “Neutral” to 3.5 stars “Attractive” to reflect our more constructive stance.
Digital Economy
Internet equities continue to benefit from sustained AI investment, with major cloud computing and cybersecurity companies offering attractive growth opportunities. However, elevated capital expenditure, financing pressures and AI disruption risks warrant selectivity, particularly in software and neoclouds. The internet platforms offer a differentiated source of return, with low valuations providing a potential downside cushion and improving margins and AI monetisation supporting upside.
ChinaHong KongSemiconductorsDigital EconomyMalaysia
Malaysia equities remain supported by stable domestic fundamentals, resilient exports and improving earnings. Data-centre EPCC projects and power-grid investments underpin near-term earnings visibility, while the KLCI50 expansion creates opportunities among small- and mid-caps. However, escalating geopolitical tensions and higher oil prices could weaken regional demand and consumer confidence. As such, we maintain our 3.0-star “Attractive” rating.
Japan
Japanese equities remain supported by resilient earnings, particularly in AI-driven semiconductor equipment and materials, while corporate governance reforms continue to improve ROE and shareholder returns. The BOJ’s September rate hike to 1.25% reinforces its monetary normalisation path. However, persistent inflation could weigh on consumption, while rising bond yields pose valuation risks. We favour large caps while selectively tilting towards small caps with stronger pricing power.
MalaysiaJapanNeutral - 2.5 Stars
Global Healthcare
Global healthcare equities have underperformed the broader market in 2026, weighed down by medical technology amid policy headwinds, competitive pressures and company-specific challenges. Meanwhile, strong innovation, funding and M&A activity continue to support pharmaceuticals, biotechnology and life sciences. With fair valuations and earnings expected to rebound in 2027, we maintain our 2.5 star neutral rating on the sector, reflecting balanced opportunities and risks.
Global HealthcareNot Attractive - 2.0 Stars
India
India remains our least preferred market in the region, given its limited exposure to the AI-driven earnings upcycle and persistent macroeconomic headwinds. Elevated oil prices are widening import costs, adding pressure on the rupee and inflation, while tighter monetary policy threatens domestic consumption and corporate margins. Valuations remain relatively expensive compared with other emerging markets, offering limited compensation for these risks.
Global Financials
Global financials remain supported by resilient bank earnings and healthy credit conditions, although growth catalysts are maturing. With limited further net interest margin expansion, net interest income increasingly depends on loan growth, which faces pressure from elevated borrowing costs. Investment banks and life insurers offer selective opportunities through capital-markets activity and higher reinvestment yields. As such, we maintain our 2.0-star “Not Attractive” rating.
ASEAN
ASEAN equities present an uneven outlook, with Singapore and Malaysia providing the strongest support through resilient earnings, electronics exports and infrastructure investment. Meanwhile, weak consumption in Thailand and currency pressures in Indonesia constrain regional growth prospects. With AI-related opportunities concentrated in selected industries, selectivity remains key. As such, we maintain our 2.0-star “Not Attractive” rating.
Europe
European equities have shown greater resilience than expected, supported by improving economic activity and a broadening earnings recovery. However, ongoing geopolitical tensions and elevated energy prices continue to fuel inflation, pressure household spending and raise the risk of further ECB tightening. While defence, infrastructure and selected tech leaders offer selective opportunities, these headwinds limit broader upside potential.
US
The US economy remains resilient, supported by growth and corporate earnings, although persistent inflation and labour market strength keep interest rate risks elevated. We favour AI-driven internet and semiconductor companies but remain cautious on consumer discretionary and unprofitable high-growth stocks. Elevated valuations relative to Asia support our underweight stance on the broader US market, favouring high-quality companies with strong balance sheets and resilient earnings.
IndiaGlobal FinancialsASEANEuropeUSTools that can empower your Investment
ETF Focus List
Discover our ETF Focus List—curated to showcase top-performing ETFs, many available through RSP with investments starting from $50.Find Out More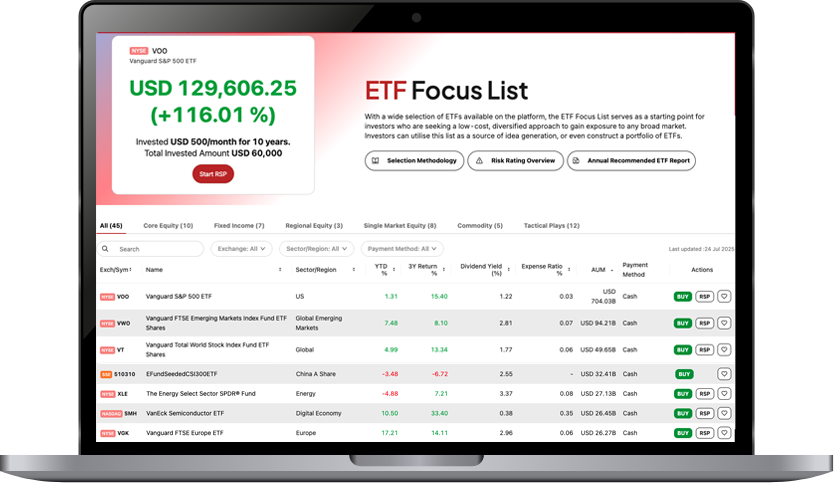
Stock Screener
Find top stocks by filtering based on key criteria tailored to your investment goals.Find Out More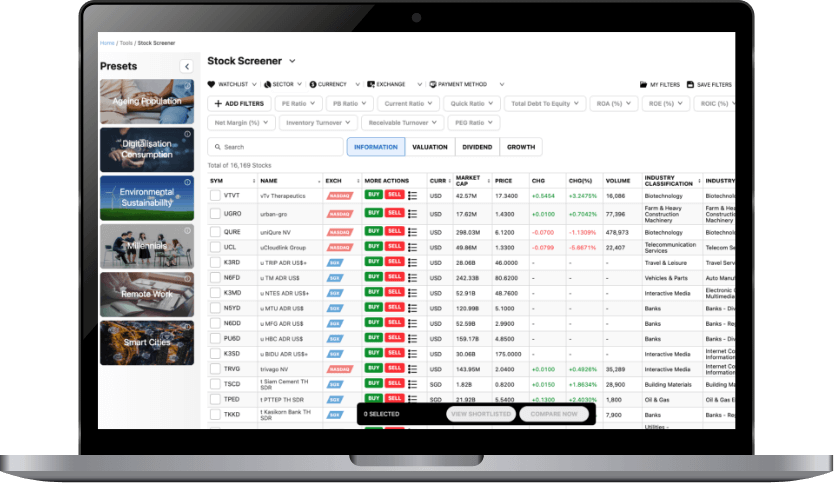
Fund & ETF Selector
Explore our Unit Trusts & ETF Selector with detailed performance data to sift through top performers or preset themes.Find Out More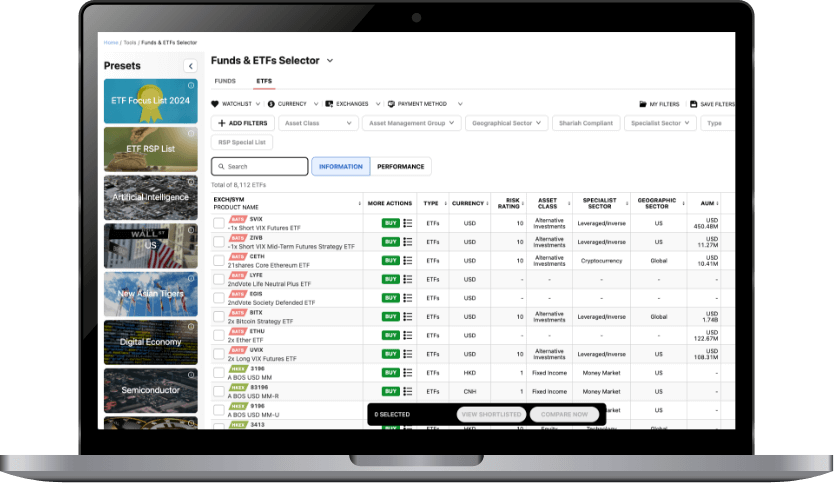
ETF Calculator
Know Where Your Money Goes. We break down every fee—so you know exactly who gets paid and how much. Use the calculator for a clear, upfront summary — no surprises.Find Out More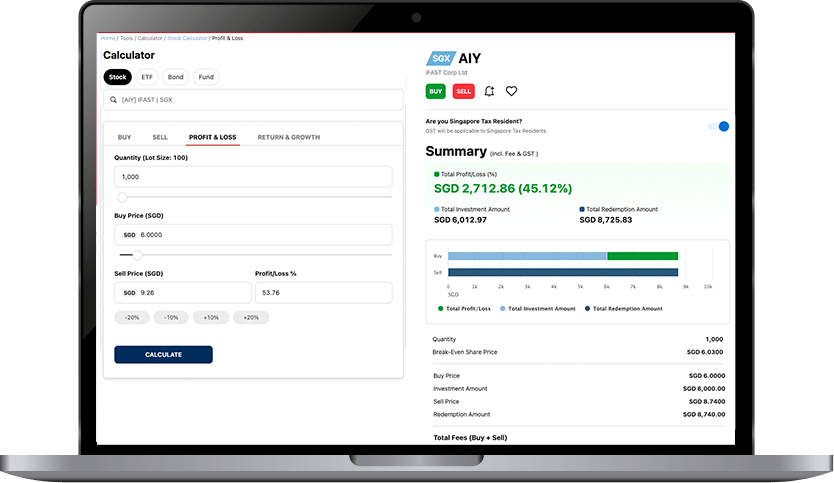
Explore other Digital Product Offerings
' fill='%23fff' stroke='%23707070' d='M0 0h80v80H0z'/%3e%3c/clipPath%3e%3c/defs%3e%3cg transform='translate(-727 -13038)' clip-path='url(%23a)'%3e%3cg data-name='signup'%3e%3cpath data-name='Path 65961' d='M767 13039.719a38.284 38.284 0 00-6.619 75.99l.156-.132v-8.677a4.7 4.7 0 00-1.507-3.443l-10.245-9.468a3.65 3.65 0 01.06-5.075 3.632 3.632 0 015.136 0l3.687 3.686v-24.444a3.129 3.129 0 013.125-3.125h.114a3.192 3.192 0 013.011 3.2v11.64h.313a3.129 3.129 0 013.125-3.125h.114a3.192 3.192 0 013.011 3.2v2.421h.313a3.129 3.129 0 013.125-3.125h.114a3.192 3.192 0 013.011 3.2v1.171h.313a3.129 3.129 0 013.124-3.113h.114a3.192 3.192 0 013.011 3.2v14.282a4.4 4.4 0 01-1.3 3.112l-2.406 2.378a4.717 4.717 0 00-1.393 3.334v7.549l.156.114a38.286 38.286 0 00-11.663-74.75z' fill='%23d5e3f4'/%3e%3cg data-name='Group 80134'%3e%3cpath data-name='Path 65962' d='M763.918 13078.2v1.68h.313a3.1 3.1 0 01.494-1.68z' fill='%23ffe177'/%3e%3cg data-name='Group 80133' fill='%23b3ceec'%3e%3cpath data-name='Path 65963' d='M757.668 13078.2h-23.98c-.2 0-.4-.011-.6-.029a6.687 6.687 0 006.673 6.259h17.907v-6.23z'/%3e%3cpath data-name='Path 65964' d='M805.226 13075.959a6.517 6.517 0 01-4.914 2.241h-30.354a3.227 3.227 0 01.523 1.758v2.421h.313a3.129 3.129 0 013.125-3.125h.114a3.192 3.192 0 013.011 3.2v1.171h.313a3.129 3.129 0 013.123-3.125h.114a3.192 3.192 0 013.011 3.2v.722h21.136a38.517 38.517 0 00.54-6.422c0-.685-.02-1.365-.055-2.041z'/%3e%3c/g%3e%3c/g%3e%3cpath data-name='Path 65965' d='M800.312 13049.562h-66.624a6.688 6.688 0 00-6.688 6.689v15.412a6.688 6.688 0 006.688 6.688h23.98v-10.2a3.129 3.129 0 013.125-3.125h.114a3.192 3.192 0 013.011 3.2v10.125h.712a3.126 3.126 0 012.726-1.6h.114a3.126 3.126 0 012.58 1.6h30.262a6.688 6.688 0 006.688-6.688v-15.413a6.688 6.688 0 00-6.688-6.688z' fill='%23fd6930'/%3e%3cpath data-name='Path 65966' d='M738.25 13071.663v-15.412a6.688 6.688 0 016.688-6.688h-11.25a6.688 6.688 0 00-6.688 6.688v15.412a6.688 6.688 0 006.688 6.688h11.25a6.688 6.688 0 01-6.688-6.688z' fill='%23ef4424'/%3e%3cg data-name='Group 80147'%3e%3cg data-name='Group 80142'%3e%3cg data-name='Group 80136'%3e%3cg data-name='Group 80135'%3e%3cpath data-name='Path 65967' d='M756.246 13072.741H752.1a3.518 3.518 0 01-3.514-3.514v-10.54a3.518 3.518 0 013.514-3.514h6.491a1.172 1.172 0 010 2.344H752.1a1.172 1.172 0 00-1.17 1.17v10.54a1.172 1.172 0 001.17 1.173h4.149a1.172 1.172 0 001.17-1.17v-4.687h-2.579a1.172 1.172 0 010-2.344h3.747a1.172 1.172 0 011.172 1.172v5.855a3.518 3.518 0 01-3.513 3.515z' fill='%23fff'/%3e%3c/g%3e%3c/g%3e%3cpath data-name='Path 65968' d='M771.725 13055.173a1.172 1.172 0 00-1.172 1.172v10.87l-6.648-11.458a1.172 1.172 0 00-2.186.588v15.224a1.172 1.172 0 102.344 0v-10.869l6.649 11.457a1.171 1.171 0 002.185-.588v-15.224a1.172 1.172 0 00-1.172-1.172z' fill='%23fff'/%3e%3cg data-name='Group 80141'%3e%3cg data-name='Group 80138'%3e%3cg data-name='Group 80137'%3e%3cpath data-name='Path 65969' d='M738.138 13072.741h-5.376a1.172 1.172 0 010-2.344h5.377a1.838 1.838 0 001.836-1.836v-1.6a1.838 1.838 0 00-1.836-1.836h-2.819a4.184 4.184 0 01-4.18-4.18v-1.6a4.184 4.184 0 014.18-4.18h5.38a1.172 1.172 0 110 2.344h-5.38a1.838 1.838 0 00-1.836 1.836v1.6a1.838 1.838 0 001.836 1.84h2.818a4.184 4.184 0 014.18 4.18v1.6a4.184 4.184 0 01-4.18 4.176z' fill='%23fff'/%3e%3c/g%3e%3c/g%3e%3cg data-name='Group 80140'%3e%3cg data-name='Group 80139'%3e%3cpath data-name='Path 65970' d='M745.45 13072.741a1.172 1.172 0 01-1.172-1.172v-15.224a1.172 1.172 0 112.344 0v15.224a1.172 1.172 0 01-1.172 1.172z' fill='%23fff'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/g%3e%3cg data-name='Group 80145'%3e%3cg data-name='Group 80144'%3e%3cg data-name='Group 80143'%3e%3cpath data-name='Path 65971' d='M792.854 13072.741a1.172 1.172 0 01-1.172-1.172v-15.224a1.172 1.172 0 011.172-1.172h5.028a4.978 4.978 0 010 9.956h-3.857v6.44a1.172 1.172 0 01-1.171 1.172zm1.172-9.956h3.856a2.634 2.634 0 100-5.268h-3.857z' fill='%23fff'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3cg data-name='Group 80146'%3e%3cpath data-name='Path 65972' d='M784.986 13072.741h-1.3a4.944 4.944 0 01-4.94-4.941v-11.455a1.172 1.172 0 112.344 0v11.455a2.6 2.6 0 002.594 2.6h1.3a2.6 2.6 0 002.596-2.6v-11.455a1.172 1.172 0 112.344 0v11.455a4.943 4.943 0 01-4.938 4.941z' fill='%23fff'/%3e%3c/g%3e%3c/g%3e%3cg data-name='Group 80148'%3e%3cpath data-name='Path 65973' d='M780.6 13080.346a3.281 3.281 0 00-3.4 3.279v-1.171a3.333 3.333 0 00-3.162-3.354 3.281 3.281 0 00-3.4 3.279v-2.426a3.333 3.333 0 00-3.163-3.353 3.281 3.281 0 00-3.4 3.279v-11.645a3.333 3.333 0 00-3.162-3.358 3.281 3.281 0 00-3.4 3.279v24.068l-3.42-3.42a3.788 3.788 0 00-5.412 5.3l10.245 9.464a4.532 4.532 0 011.455 3.333v8.812a38.488 38.488 0 0018.281-1.242v-7.663a4.531 4.531 0 011.346-3.223l2.407-2.378a4.531 4.531 0 001.346-3.223v-14.283a3.333 3.333 0 00-3.161-3.354z' fill='%23ffb09e'/%3e%3c/g%3e%3cg data-name='Group 80149'%3e%3cpath data-name='Path 65974' d='M764.4 13116.193v-10.546a4.531 4.531 0 00-1.457-3.328l-10.243-9.465a3.788 3.788 0 01-.21-5 3.788 3.788 0 00-3.811 6.246l10.245 9.464a4.532 4.532 0 011.457 3.336v8.812a38.454 38.454 0 004.019.481z' fill='%23f89580'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "signupIcon")
' fill='%23fff' stroke='%23707070' d='M0 0h80v80H0z'/%3e%3c/clipPath%3e%3c/defs%3e%3cg transform='translate(-678 -13148)' clip-path='url(%23a)'%3e%3cg transform='translate(678.061 13147.142)'%3e%3cpath data-name='Path 65975' d='M38.224.858A38.063 38.063 0 0021.2 4.851L5.45 58.761A38.225 38.225 0 1038.224.858z' fill='%233b3868'/%3e%3cpath data-name='Path 65976' d='M76.531 4.851H21.2A38.351 38.351 0 0010.1 13.2h58.3a3.081 3.081 0 013.078 3.078v34.407h5.058a3.353 3.353 0 003.349-3.349V8.2a3.353 3.353 0 00-3.349-3.349z' fill='%2349ce8b'/%3e%3cpath data-name='Path 65977' d='M25.764 4.851H21.2A38.351 38.351 0 0010.1 13.2h18.1a1.159 1.159 0 00-.366-.574A2.629 2.629 0 0127 9.683a1.19 1.19 0 00-.385-1.254 2.772 2.772 0 01-.915-3.173 1.248 1.248 0 00.066-.405z' fill='%2336b277'/%3e%3cpath data-name='Path 65978' d='M74.474 8.919H14.748A38.448 38.448 0 0010.1 13.2h58.3a3.081 3.081 0 013.078 3.078v30.339h3a1.338 1.338 0 001.338-1.338V10.257a1.339 1.339 0 00-1.338-1.338z' fill='%2336b277'/%3e%3cpath data-name='Path 65979' d='M10.1 13.2h18.1a1.159 1.159 0 00-.366-.574A2.629 2.629 0 0127 9.683a1.163 1.163 0 00-.035-.764H14.748A38.436 38.436 0 0010.1 13.2z' fill='%23279b61'/%3e%3cpath data-name='Path 65980' d='M74.474 8.919H63.9a10.373 10.373 0 00.183 4.279h4.311a3.081 3.081 0 013.078 3.078v4.354a10.354 10.354 0 004.339.2V10.257a1.338 1.338 0 00-1.338-1.338z' fill='%23279b61'/%3e%3cpath data-name='Path 65981' d='M68.4 12.927H10.352a38.232 38.232 0 00-4.9 45.834h62.943a3.353 3.353 0 003.349-3.349V16.276a3.353 3.353 0 00-3.344-3.349z' fill='%2349ce8b'/%3e%3cpath data-name='Path 65982' d='M0 39.082a38.044 38.044 0 005.45 19.679H32.5V51.3a1.535 1.535 0 00-.562-1.166 1.688 1.688 0 01-.607-1.38 1.575 1.575 0 00-.669-1.333 3 3 0 01-1.3-2.757 1.527 1.527 0 00-.068-.592l-.157-.494a1.543 1.543 0 01.1-1.175c.733-1.424 2.331-5.267-.989-6.562A4.9 4.9 0 0125 30.86a1.533 1.533 0 00-.669-1.318 4.027 4.027 0 01-1.888-3.726 1.56 1.56 0 00-.957-1.529 5.5 5.5 0 01-3.321-6.466 1.542 1.542 0 00-.436-1.362 3.005 3.005 0 01-.979-2.419 1.539 1.539 0 00-.36-1.113h-6.038A38.085 38.085 0 000 39.082z' fill='%2336b277'/%3e%3cpath data-name='Path 65983' d='M66.338 16.995H7.025a38.261 38.261 0 00-3.7 37.7h63.012a1.338 1.338 0 001.338-1.338V18.333a1.338 1.338 0 00-1.338-1.338z' fill='%2336b277'/%3e%3cg data-name='Group 80150' fill='%23279b61'%3e%3cpath data-name='Path 65984' d='M0 39.082a38.079 38.079 0 003.325 15.611H32.5V51.3a1.535 1.535 0 00-.562-1.166 1.688 1.688 0 01-.607-1.38 1.575 1.575 0 00-.669-1.333 3 3 0 01-1.3-2.757 1.527 1.527 0 00-.068-.592l-.157-.494a1.543 1.543 0 01.1-1.175c.733-1.424 2.331-5.267-.989-6.562A4.9 4.9 0 0125 30.86a1.533 1.533 0 00-.669-1.318 4.027 4.027 0 01-1.888-3.726 1.56 1.56 0 00-.957-1.529 5.5 5.5 0 01-3.321-6.466 1.514 1.514 0 00-.086-.826H7.025A38.043 38.043 0 000 39.082z'/%3e%3cpath data-name='Path 65985' d='M67.676 18.333v10.573a10.348 10.348 0 01-11.911-11.911h10.572a1.338 1.338 0 011.338 1.338z'/%3e%3cpath data-name='Path 65986' d='M67.676 53.354V42.782a10.348 10.348 0 00-11.911 11.91h10.572a1.338 1.338 0 001.339-1.338z'/%3e%3ccircle data-name='Ellipse 7341' cx='12.475' cy='12.475' r='12.475' transform='translate(15.772 23.368)'/%3e%3c/g%3e%3cpath data-name='Path 65987' d='M30.663 47.424a3 3 0 01-1.3-2.757 1.527 1.527 0 00-.068-.592l-.157-.494a1.543 1.543 0 01.1-1.175c.733-1.424 2.331-5.267-.989-6.562A4.9 4.9 0 0125 30.86a1.533 1.533 0 00-.669-1.318 4.027 4.027 0 01-1.888-3.726 1.539 1.539 0 00-.224-.9 12.475 12.475 0 008.925 23.058 1.567 1.567 0 00-.485-.553z' fill='%231c8c51'/%3e%3ccircle data-name='Ellipse 7342' cx='15.219' cy='15.219' r='15.219' transform='rotate(-82.875 66.287 12.878)' fill='%23ffdd40'/%3e%3cpath data-name='Path 65988' d='M47.05 63.8a15.219 15.219 0 0025.707 11.031.484.484 0 00-.254-.115 1.126 1.126 0 01-1.127-1.169.491.491 0 00-.376-.475 1.477 1.477 0 01-1.24-1.484.481.481 0 00-.4-.459c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.184-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.489.489 0 00-.33-.528 1.483 1.483 0 01-.994-1.781.47.47 0 00-.283-.505 1.254 1.254 0 01-.737-1.341.489.489 0 00-.076-.3A15.217 15.217 0 0047.05 63.8z' fill='%23ffb332'/%3e%3ccircle data-name='Ellipse 7343' cx='10.477' cy='10.477' r='10.477' transform='rotate(-45 100.733 -25.368)' fill='%23fceca9'/%3e%3cpath data-name='Path 65989' d='M69.622 71.266a.5.5 0 00-.257-.137c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.184-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.476.476 0 00-.077-.333 10.479 10.479 0 1012.387 16.657z' fill='%23ffdd40'/%3e%3cpath data-name='Path 65990' d='M62.273 53.32A10.479 10.479 0 1151.794 63.8a10.479 10.479 0 0110.479-10.48m0-2.609A13.088 13.088 0 1075.36 63.8a13.1 13.1 0 00-13.087-13.089z' fill='%23ffb332'/%3e%3cpath data-name='Path 65991' d='M62.273 76.887a13.037 13.037 0 009.016-3.614.487.487 0 00-.287-.2 1.477 1.477 0 01-1.24-1.484.466.466 0 00-.14-.321A10.478 10.478 0 1157.235 54.61a.5.5 0 00-.253-.2 1.483 1.483 0 01-.994-1.781.459.459 0 00-.046-.283 13.084 13.084 0 006.331 24.537z' fill='%23ff9100'/%3e%3ccircle data-name='Ellipse 7344' cx='15.223' cy='15.223' r='15.223' transform='translate(35.854 48.576)' fill='%23ffdd40'/%3e%3cpath data-name='Path 65992' d='M35.854 63.8a15.219 15.219 0 0025.707 11.031.484.484 0 00-.254-.115 1.126 1.126 0 01-1.127-1.169.491.491 0 00-.374-.475 1.477 1.477 0 01-1.24-1.484.482.482 0 00-.4-.459c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.489.489 0 00-.33-.528 1.483 1.483 0 01-.994-1.781.47.47 0 00-.283-.505 1.255 1.255 0 01-.737-1.341.489.489 0 00-.076-.3A15.217 15.217 0 0035.854 63.8z' fill='%23ffb332'/%3e%3ccircle data-name='Ellipse 7345' cx='10.479' cy='10.479' r='10.479' transform='rotate(-66.485 71.44 6.162)' fill='%23fceca9'/%3e%3cpath data-name='Path 65993' d='M58.426 71.266a.5.5 0 00-.257-.137c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.476.476 0 00-.077-.333 10.479 10.479 0 1012.387 16.657z' fill='%23ffdd40'/%3e%3cpath data-name='Path 65994' d='M51.077 53.32A10.479 10.479 0 1140.6 63.8a10.479 10.479 0 0110.477-10.48m0-2.609A13.088 13.088 0 1064.164 63.8a13.1 13.1 0 00-13.087-13.089z' fill='%23ffb332'/%3e%3cpath data-name='Path 65995' d='M51.077 76.887a13.037 13.037 0 009.016-3.614.487.487 0 00-.287-.2 1.477 1.477 0 01-1.24-1.484.466.466 0 00-.14-.321A10.478 10.478 0 1146.039 54.61a.505.505 0 00-.253-.2 1.483 1.483 0 01-.994-1.781.459.459 0 00-.046-.283 13.084 13.084 0 006.331 24.537z' fill='%23ff9100'/%3e%3ccircle data-name='Ellipse 7346' cx='15.226' cy='15.226' r='15.226' transform='rotate(-82.65 55.19 25.474)' fill='%23ffdd40'/%3e%3cpath data-name='Path 65996' d='M24.658 63.8a15.219 15.219 0 0025.707 11.031.484.484 0 00-.254-.115 1.126 1.126 0 01-1.127-1.169.491.491 0 00-.374-.475 1.477 1.477 0 01-1.24-1.484.481.481 0 00-.4-.459c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.489.489 0 00-.33-.528 1.483 1.483 0 01-.994-1.781.47.47 0 00-.283-.505 1.255 1.255 0 01-.737-1.341.49.49 0 00-.076-.3A15.217 15.217 0 0024.658 63.8z' fill='%23ffb332'/%3e%3ccircle data-name='Ellipse 7347' cx='10.477' cy='10.477' r='10.477' transform='rotate(-45 89.536 1.657)' fill='%23fceca9'/%3e%3cpath data-name='Path 65997' d='M47.231 71.266a.5.5 0 00-.257-.137c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.476.476 0 00-.077-.333 10.479 10.479 0 1012.387 16.657z' fill='%23ffdd40'/%3e%3cpath data-name='Path 65998' d='M39.881 53.32A10.479 10.479 0 1129.4 63.8a10.479 10.479 0 0110.481-10.48m0-2.609A13.088 13.088 0 1052.969 63.8a13.1 13.1 0 00-13.088-13.089z' fill='%23ffb332'/%3e%3cpath data-name='Path 65999' d='M39.881 76.887a13.037 13.037 0 009.019-3.615.487.487 0 00-.287-.2 1.477 1.477 0 01-1.24-1.484.466.466 0 00-.14-.321 10.478 10.478 0 11-12.39-16.657.5.5 0 00-.253-.2 1.483 1.483 0 01-.994-1.781.459.459 0 00-.046-.283 13.084 13.084 0 006.331 24.537z' fill='%23ff9100'/%3e%3cg data-name='Group 80151'%3e%3cpath data-name='Path 66000' d='M39.881 71.7a1.3 1.3 0 01-1.3-1.3v-1.719a1.3 1.3 0 012.609 0v1.711a1.3 1.3 0 01-1.309 1.308z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 80152'%3e%3cpath data-name='Path 66001' d='M39.881 60.114a1.3 1.3 0 01-1.3-1.3v-1.6a1.3 1.3 0 012.609 0v1.6a1.3 1.3 0 01-1.309 1.3z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 80153'%3e%3cpath data-name='Path 66002' d='M39.722 69.986a4.726 4.726 0 01-3.022-.862 1.3 1.3 0 011.428-2.183 2.284 2.284 0 001.686.436 1.213 1.213 0 001.213-1.03.843.843 0 00-.638-1.015l-.026-.01-1.874-.708a3.45 3.45 0 01-2.327-3.9 3.839 3.839 0 013.768-3.207 4.8 4.8 0 013.132.861 1.3 1.3 0 01-1.428 2.183 2.28 2.28 0 00-1.686-.436 1.213 1.213 0 00-1.213 1.03.843.843 0 00.638 1.015l.026.01 1.874.708a3.449 3.449 0 012.327 3.9 3.839 3.839 0 01-3.768 3.207h-.11z' fill='%23ffb332'/%3e%3c/g%3e%3cpath data-name='Path 66003' d='M52.763 37.2h-4.605a1.356 1.356 0 010-2.712h4.605a1.356 1.356 0 010 2.712z' fill='%2349ce8b'/%3e%3cpath data-name='Path 66004' d='M8.338 37.2H3.733a1.356 1.356 0 010-2.712h4.605a1.356 1.356 0 110 2.712z' fill='%2336b277'/%3e%3cg data-name='Group 80154'%3e%3cpath data-name='Path 66005' d='M28.248 45.049a1.356 1.356 0 01-1.356-1.356v-2.037a1.356 1.356 0 112.712 0v2.037a1.356 1.356 0 01-1.356 1.356z' fill='%2349ce8b'/%3e%3c/g%3e%3cg data-name='Group 80155'%3e%3cpath data-name='Path 66006' d='M28.248 31.26a1.356 1.356 0 01-1.356-1.36v-1.91a1.356 1.356 0 112.712 0v1.91a1.356 1.356 0 01-1.356 1.36z' fill='%2349ce8b'/%3e%3c/g%3e%3cg data-name='Group 80156'%3e%3cpath data-name='Path 66007' d='M28.051 43.012a5.389 5.389 0 01-3.482-.994 1.356 1.356 0 011.485-2.27 2.9 2.9 0 002.116.551 1.649 1.649 0 001.637-1.391 1.2 1.2 0 00-.888-1.427l-.027-.01-2.232-.844a3.915 3.915 0 01-2.645-4.427 4.379 4.379 0 014.293-3.653 5.457 5.457 0 013.619.993 1.356 1.356 0 01-1.485 2.27 2.892 2.892 0 00-2.116-.551 1.649 1.649 0 00-1.637 1.391 1.2 1.2 0 00.888 1.426l.027.01 2.232.844a3.915 3.915 0 012.644 4.428 4.379 4.379 0 01-4.293 3.653h-.137z' fill='%2367e8a4'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "autosweepIcon")
'%3e%3ccircle data-name='Ellipse 8432' cx='15.226' cy='15.226' r='15.226' transform='rotate(-82.65 55.19 25.474)' fill='%23ffdd40'/%3e%3cpath data-name='Path 173320' d='M24.658 63.8a15.219 15.219 0 0025.707 11.031.484.484 0 00-.254-.115 1.126 1.126 0 01-1.127-1.169.491.491 0 00-.374-.475 1.477 1.477 0 01-1.24-1.484.481.481 0 00-.4-.459c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.489.489 0 00-.33-.528 1.483 1.483 0 01-.994-1.781.47.47 0 00-.283-.505 1.255 1.255 0 01-.737-1.341.49.49 0 00-.076-.3A15.217 15.217 0 0024.658 63.8z' fill='%23ffb332'/%3e%3ccircle data-name='Ellipse 8433' cx='10.477' cy='10.477' r='10.477' transform='rotate(-45 89.536 1.657)' fill='%23fceca9'/%3e%3cpath data-name='Path 173321' d='M47.231 71.266a.5.5 0 00-.257-.137c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.476.476 0 00-.077-.333 10.479 10.479 0 1012.387 16.657z' fill='%23ffdd40'/%3e%3cpath data-name='Path 173322' d='M39.881 53.32A10.479 10.479 0 1129.4 63.8a10.479 10.479 0 0110.481-10.48m0-2.609A13.088 13.088 0 1052.969 63.8a13.1 13.1 0 00-13.088-13.089z' fill='%23ffb332'/%3e%3cpath data-name='Path 173323' d='M39.881 76.887a13.037 13.037 0 009.019-3.615.487.487 0 00-.287-.2 1.477 1.477 0 01-1.24-1.484.466.466 0 00-.14-.321 10.478 10.478 0 11-12.39-16.657.5.5 0 00-.253-.2 1.483 1.483 0 01-.994-1.781.459.459 0 00-.046-.283 13.084 13.084 0 006.331 24.537z' fill='%23ff9100'/%3e%3cg data-name='Group 137650'%3e%3cpath data-name='Path 173324' d='M39.881 71.7a1.3 1.3 0 01-1.3-1.3v-1.719a1.3 1.3 0 012.609 0v1.711a1.3 1.3 0 01-1.309 1.308z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 137651'%3e%3cpath data-name='Path 173325' d='M39.881 60.114a1.3 1.3 0 01-1.3-1.3v-1.6a1.3 1.3 0 012.609 0v1.6a1.3 1.3 0 01-1.309 1.3z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 137652'%3e%3cpath data-name='Path 173326' d='M39.722 69.986a4.726 4.726 0 01-3.022-.862 1.3 1.3 0 011.428-2.183 2.284 2.284 0 001.686.436 1.213 1.213 0 001.213-1.03.843.843 0 00-.638-1.015l-.026-.01-1.874-.708a3.45 3.45 0 01-2.327-3.9 3.839 3.839 0 013.768-3.207 4.8 4.8 0 013.132.861 1.3 1.3 0 01-1.428 2.183 2.28 2.28 0 00-1.686-.436 1.213 1.213 0 00-1.213 1.03.843.843 0 00.638 1.015l.026.01 1.874.708a3.449 3.449 0 012.327 3.9 3.839 3.839 0 01-3.768 3.207h-.11z' fill='%23ffb332'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e "stocksEtfBondsIcon")
'%3e%3ccircle data-name='Ellipse 8432' cx='15.226' cy='15.226' r='15.226' transform='rotate(-82.65 55.19 25.474)' fill='%23ffdd40'/%3e%3cpath data-name='Path 173320' d='M24.658 63.8a15.219 15.219 0 0025.707 11.031.484.484 0 00-.254-.115 1.126 1.126 0 01-1.127-1.169.491.491 0 00-.374-.475 1.477 1.477 0 01-1.24-1.484.481.481 0 00-.4-.459c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.489.489 0 00-.33-.528 1.483 1.483 0 01-.994-1.781.47.47 0 00-.283-.505 1.255 1.255 0 01-.737-1.341.49.49 0 00-.076-.3A15.217 15.217 0 0024.658 63.8z' fill='%23ffb332'/%3e%3ccircle data-name='Ellipse 8433' cx='10.477' cy='10.477' r='10.477' transform='rotate(-45 89.536 1.657)' fill='%23fceca9'/%3e%3cpath data-name='Path 173321' d='M47.231 71.266a.5.5 0 00-.257-.137c-3.724-.715-3.488-3.618-3.394-4.235a.481.481 0 00-.03-.257c-.183-.442-.953-1.824-3.668-2.838-2.654-.991-2.72-3.8-2.649-4.824a.487.487 0 00-.335-.492 3.031 3.031 0 01-1.977-3.541.476.476 0 00-.077-.333 10.479 10.479 0 1012.387 16.657z' fill='%23ffdd40'/%3e%3cpath data-name='Path 173322' d='M39.881 53.32A10.479 10.479 0 1129.4 63.8a10.479 10.479 0 0110.481-10.48m0-2.609A13.088 13.088 0 1052.969 63.8a13.1 13.1 0 00-13.088-13.089z' fill='%23ffb332'/%3e%3cpath data-name='Path 173323' d='M39.881 76.887a13.037 13.037 0 009.019-3.615.487.487 0 00-.287-.2 1.477 1.477 0 01-1.24-1.484.466.466 0 00-.14-.321 10.478 10.478 0 11-12.39-16.657.5.5 0 00-.253-.2 1.483 1.483 0 01-.994-1.781.459.459 0 00-.046-.283 13.084 13.084 0 006.331 24.537z' fill='%23ff9100'/%3e%3cg data-name='Group 137650'%3e%3cpath data-name='Path 173324' d='M39.881 71.7a1.3 1.3 0 01-1.3-1.3v-1.719a1.3 1.3 0 012.609 0v1.711a1.3 1.3 0 01-1.309 1.308z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 137651'%3e%3cpath data-name='Path 173325' d='M39.881 60.114a1.3 1.3 0 01-1.3-1.3v-1.6a1.3 1.3 0 012.609 0v1.6a1.3 1.3 0 01-1.309 1.3z' fill='%23ff9100'/%3e%3c/g%3e%3cg data-name='Group 137652'%3e%3cpath data-name='Path 173326' d='M39.722 69.986a4.726 4.726 0 01-3.022-.862 1.3 1.3 0 011.428-2.183 2.284 2.284 0 001.686.436 1.213 1.213 0 001.213-1.03.843.843 0 00-.638-1.015l-.026-.01-1.874-.708a3.45 3.45 0 01-2.327-3.9 3.839 3.839 0 013.768-3.207 4.8 4.8 0 013.132.861 1.3 1.3 0 01-1.428 2.183 2.28 2.28 0 00-1.686-.436 1.213 1.213 0 00-1.213 1.03.843.843 0 00.638 1.015l.026.01 1.874.708a3.449 3.449 0 012.327 3.9 3.839 3.839 0 01-3.768 3.207h-.11z' fill='%23ffb332'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e "realtimeCurrExcIcon")


' fill='%23fff' stroke='%23707070' d='M0 0h80v80H0z'/%3e%3c/clipPath%3e%3c/defs%3e%3cg transform='translate(-546 -13134)' clip-path='url(%23a)'%3e%3cg transform='translate(546 13134)'%3e%3ccircle data-name='Ellipse 7348' cx='40' cy='40' r='40' fill='%235c5e70'/%3e%3cpath data-name='Path 66063' d='M21.359.021a21.838 21.838 0 00-16.052 36.1 6.606 6.606 0 011.2 6.541l-1.438 4.025a1.4 1.4 0 002.16 1.595l5.1-3.811a6.68 6.68 0 015.3-1.19 21.838 21.838 0 103.73-43.26z' fill='%23ff525d'/%3e%3cpath data-name='Path 66064' d='M71.065 56.216a8.179 8.179 0 00-1.465 7.971l.691 1.935q-1.308 1.516-2.763 2.9l-4.291-3.2a8.094 8.094 0 00-6.32-1.473 25.46 25.46 0 01-4.2.5A23.81 23.81 0 1171.06 56.22z' fill='%23ffd15c'/%3e%3cg data-name='Group 80191' fill='%23f9eed7'%3e%3cpath data-name='Path 66065' d='M56.083 54.205a3.435 3.435 0 01-3.34 3.383 3.384 3.384 0 113.34-3.383zm-.835-8.349c0 1.362-1.494 1.934-2.549 1.934-1.406 0-2.593-.571-2.593-1.934 0-5.229-.615-12.743-.615-17.973 0-1.714 1.406-2.68 3.208-2.68 1.714 0 3.164.967 3.164 2.68.001 5.23-.614 12.744-.614 17.973z'/%3e%3cpath data-name='Path 66066' d='M25.586 21c-2.216 1.733-2.257 2.942-2.257 5.038 0 .766-.4 1.652-2.378 1.652-1.652 0-2.216-.6-2.216-2.7a7.378 7.378 0 012.7-6.126c1.33-1.128 3.587-2.378 3.587-4.554 0-1.854-1.612-2.741-3.627-2.741-4.111 0-3.224 3.1-5.4 3.1a2.311 2.311 0 01-2.418-2.3c0-2.176 2.5-5.4 7.94-5.4 5.159 0 8.584 2.861 8.584 6.65S26.674 20.156 25.586 21zM24.1 33.577a3.131 3.131 0 01-3.1 3.1 3.1 3.1 0 010-6.206 3.131 3.131 0 013.1 3.106z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "faq02Icon")

' d='M0 0h300v57H0z'/%3e%3c/svg%3e "sgFsmLogoEnIcon")


'%3e%3cpath fill='%23fff' d='M0 0h21.6v21.6H0z'/%3e%3cg data-name='141-singapore'%3e%3cpath data-name='Rectangle 6502' fill='%23f0f0f0' d='M0 0h22v22H0z'/%3e%3cpath data-name='Rectangle 6503' fill='%23d80027' d='M0 0h22v10H0z'/%3e%3cg data-name='Group 21092' fill='%23f0f0f0'%3e%3cpath data-name='Path 14455' d='M2.917 5.365A3.128 3.128 0 015.374 2.31a3.128 3.128 0 100 6.11 3.128 3.128 0 01-2.457-3.055z'/%3e%3cpath data-name='Path 14456' d='M6.939 2.46l.222.683h.718l-.581.422.222.683-.581-.422-.581.422.222-.683-.581-.422h.718z'/%3e%3cpath data-name='Path 14457' d='M5.193 3.801l.222.683h.718l-.581.422.222.683-.581-.422-.581.422.222-.683-.581-.422h.718z'/%3e%3cpath data-name='Path 14458' d='M8.68 3.801l.222.683h.718l-.581.422.222.683-.581-.422-.581.422.222-.683-.581-.422h.718z'/%3e%3cpath data-name='Path 14459' d='M8.01 5.811l.222.683h.718l-.581.422.222.683-.581-.422-.581.422.222-.683-.581-.422h.718z'/%3e%3cpath data-name='Path 14460' d='M5.863 5.811l.222.683h.718l-.581.422.222.683-.581-.422-.581.422.222-.683-.581-.422h.718z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e "singaporeIcon")